
Meta Description: How long does it take to save $100,000 on a $4,000 monthly income? Discover realistic savings rates, timelines, budgeting strategies, and ways to reach your goal faster.
Saving $100,000 is a major financial milestone. But if you earn $4,000 per month, you may wonder whether reaching six figures in savings is realistic — and how many years it could take.
The good news is that you don’t need a six-figure salary to build $100,000 in savings. What matters most is how much you consistently save, how quickly your income grows, and whether your money earns a return while you’re building the balance.
Let’s break down the numbers and create a realistic path toward your first $100,000.
How Much Can You Save on a $4,000 Monthly Income?
A $4,000 monthly income gives you $48,000 per year before taxes if $4,000 represents your gross monthly salary.
Your actual take-home pay will depend on taxes, insurance, retirement contributions, and other deductions. For that reason, your savings target should be based on your net income and actual monthly expenses.
For example, imagine you take home $3,200 per month and manage to save $800.
That’s a 25% savings rate.
At that pace:
$800 × 12 = $9,600 per year
Without considering investment growth, it would take approximately 10.4 years to save $100,000.
That may sound like a long time, but increasing your savings rate can dramatically shorten the timeline.
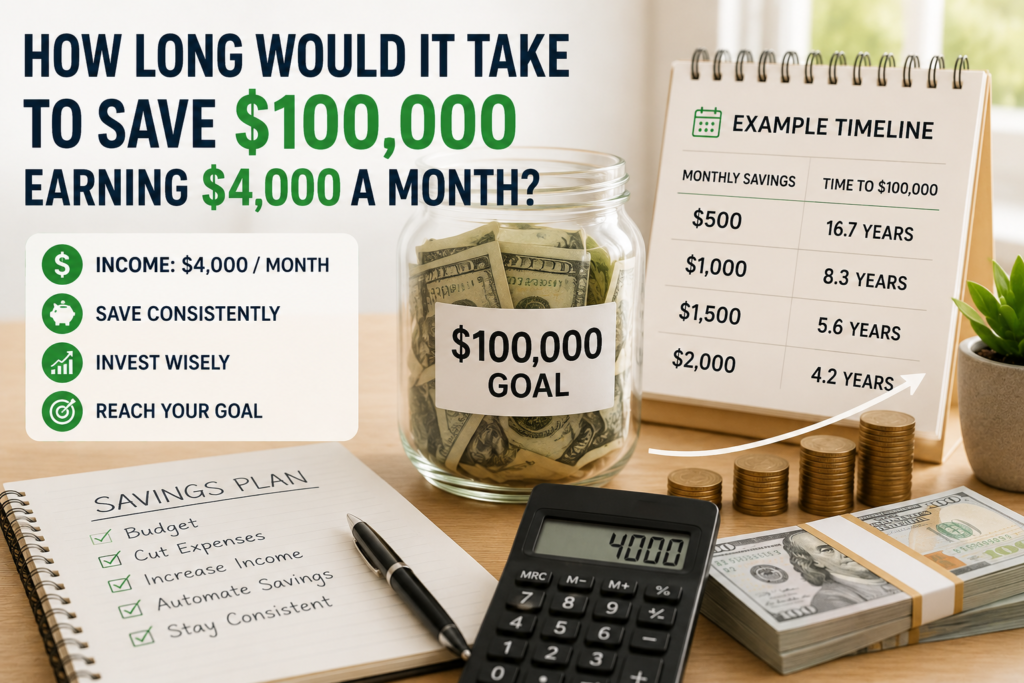
How Long It Takes to Save $100,000
Your timeline depends primarily on your monthly savings.
| Monthly Savings | Annual Savings | Time to $100,000 |
|---|---|---|
| $300 | $3,600 | 27.8 years |
| $500 | $6,000 | 16.7 years |
| $750 | $9,000 | 11.1 years |
| $1,000 | $12,000 | 8.3 years |
| $1,250 | $15,000 | 6.7 years |
| $1,500 | $18,000 | 5.6 years |
| $2,000 | $24,000 | 4.2 years |
These figures assume you’re simply accumulating cash and don’t include investment returns.
The key takeaway is simple: the amount you save each month matters enormously.
The 20% Savings Strategy
A common starting point is saving around 20% of your income.
If you earn $4,000 per month, that’s:
$4,000 × 20% = $800 per month
Saving $800 monthly would give you $9,600 annually. Without investment growth, your $100,000 goal would take just over 10 years.
For someone starting from zero, this is a realistic but relatively slow path.
However, the goal shouldn’t necessarily be to remain at 20%.
As your income increases, you can increase your savings rate without dramatically changing your lifestyle.
What If You Save 30%?
Saving 30% of a $4,000 monthly income means putting away:
$4,000 × 30% = $1,200 per month
That equals $14,400 per year.
At that rate, you could reach $100,000 in approximately 6.9 years, assuming no investment growth.
That’s more than three years faster than saving $800 per month.
The difference demonstrates why controlling lifestyle inflation is so powerful.
If your income rises from $4,000 to $5,000 per month, you don’t necessarily need to increase your spending by $1,000. Saving a large portion of that raise can dramatically accelerate your progress.
Can You Save $100,000 in Five Years?
Yes, but it requires a much more aggressive savings rate.
To save $100,000 in exactly five years without investment returns, you would need:
$100,000 ÷ 60 months = $1,667 per month
That’s approximately 42% of a $4,000 monthly income.
For many people, saving $1,667 every month would be difficult. But it becomes more achievable when you combine several strategies:
- Reduce housing costs
- Eliminate high-interest debt
- Cut unnecessary subscriptions
- Cook more meals at home
- Avoid frequent vehicle upgrades
- Increase your income
- Direct bonuses and tax refunds toward savings
- Automate your savings
You don’t necessarily need to save $1,667 from your paycheck alone. Additional income can make a significant difference.
Investing Can Shorten the Timeline
There’s another important factor: your money doesn’t necessarily have to sit in cash while you work toward $100,000.
Long-term investments have historically provided opportunities for growth, although returns are never guaranteed and investments can lose value.
For example, consistently investing $1,000 per month and earning an average annual return could potentially allow you to reach $100,000 sooner than simply saving $1,000 in cash every month.
However, investment returns fluctuate. You should also keep emergency savings in an appropriate liquid account rather than investing money you’ll need in the short term.
The goal isn’t to take unnecessary risks. It’s to give long-term money an opportunity to grow.
The Biggest Expense Usually Matters Most
If you’re serious about reaching $100,000, focus on your largest expenses first.
Housing is often the biggest one.
A person who reduces monthly housing costs by $400 can potentially redirect $4,800 per year toward their financial goal.
Transportation is another major category. A lower car payment, cheaper insurance, and reduced fuel costs can free up hundreds of dollars every month.
Small expenses matter, but optimizing your biggest recurring bills often produces the fastest results.
Increase Your Income Instead of Only Cutting Expenses
There is a limit to how much you can cut from your budget.
There isn’t necessarily a limit to how much you can earn.
Consider:
- Asking for a raise
- Developing a higher-paying skill
- Changing employers
- Freelancing
- Starting a side business
- Selling unused items
- Taking on occasional overtime
Even an additional $500 per month can have a major impact.
If you earn $4,000 and save $1,000, you’re already putting away 25% of your income. If you generate another $500 and save most of it, your monthly savings could approach $1,500.
That can reduce your timeline to roughly 5½ years, before considering investment growth.
Don’t Forget Your First $10,000
Saving the first $10,000 can feel much harder than reaching $100,000.
At the beginning, you may have no emergency fund, outstanding debt, or little financial momentum.
Once you establish a consistent savings habit, however, progress can become easier.
Think about the goal in smaller milestones:
$1,000 → $5,000 → $10,000 → $25,000 → $50,000 → $75,000 → $100,000
Each milestone represents progress and gives you motivation to continue.
The Bottom Line
So, how long would it take to save $100,000 earning $4,000 a month?
The answer depends on your savings rate.
If you save $500 per month, it could take nearly 17 years. Save $1,000 monthly, and the timeline falls to about 8.3 years. Save $1,500, and you’re looking at roughly 5.6 years.
But your income doesn’t have to remain at $4,000 forever.
The most effective strategy is to control your expenses, increase your income, avoid lifestyle inflation, automate your savings, and invest appropriately for long-term goals.
Reaching $100,000 isn’t about making one huge financial decision. It’s about making thousands of small, consistent decisions that move your money in the right direction.
Start with what you can save today. Then increase that number every time your financial situation improves. Click in Read Next: