
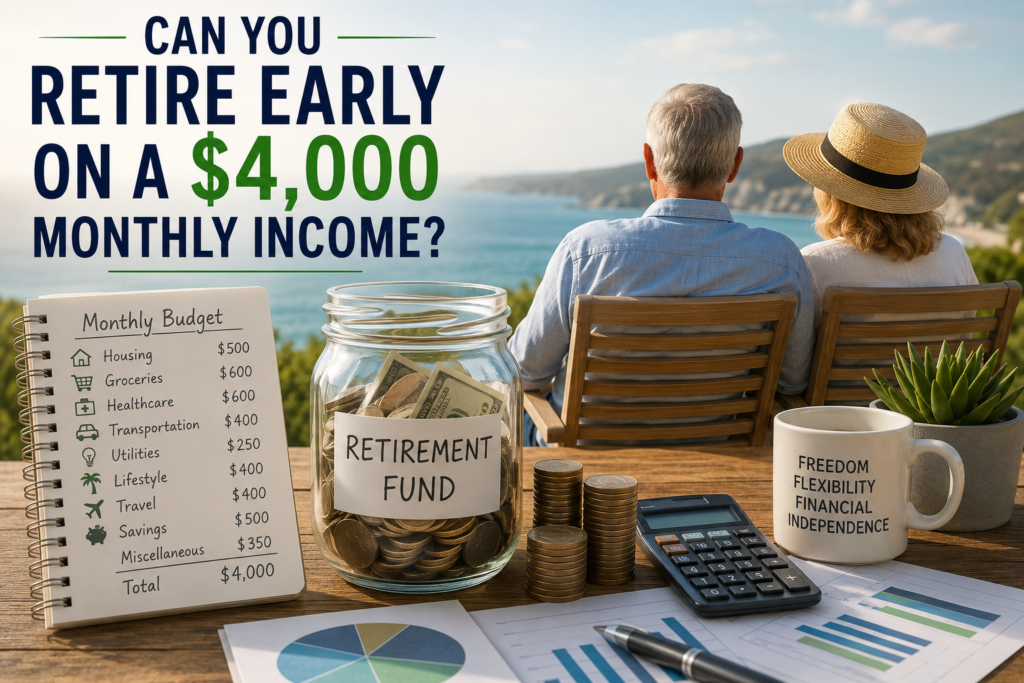
Meta Description: Can you retire early on $4,000 a month? Learn how much you need to save, where your money will go, healthcare considerations, and strategies to make early retirement sustainable.
Retiring early is one of the most appealing financial goals: leaving the traditional 9-to-5 behind, gaining control over your time, and having the freedom to travel, pursue hobbies, or simply enjoy life on your own terms.
But early retirement ultimately comes down to one question: Can $4,000 a month actually support the lifestyle you want?
The answer is yes for some people—but not automatically.
A $4,000 monthly income gives you $48,000 per year before considering taxes or other adjustments. Whether that amount is enough depends on several critical factors, including your savings, housing costs, healthcare expenses, location, lifestyle, and ability to generate additional income when necessary.
Here’s what you need to know.
The Short Answer: Yes, But Your Numbers eestMatter
For many households, $4,000 per month can support an early-retirement lifestyle. The situation becomes significantly easier if you:
- Own your home outright
- Have little or no debt
- Live in a relatively affordable area
- Have substantial retirement and investment savings
- Keep discretionary spending under control
- Have access to affordable healthcare
- Are willing to earn occasional part-time income if necessary
For a single person living in an expensive U.S. city, however, $4,000 per month may provide very little flexibility.
The most important lesson is simple:
Early retirement isn’t determined by income alone. It’s determined by the relationship between your income, expenses, assets, and lifestyle.
What Does $4,000 a Month Really Buy?
The purchasing power of $4,000 varies dramatically depending on where you live.
High-Cost U.S. Cities
In places such as New York, San Francisco, Boston, or other expensive metropolitan areas, $4,000 can disappear quickly.
Rent, utilities, groceries, transportation, insurance, and healthcare can consume most of your monthly budget before you spend anything on travel or entertainment.
Early retirement in this environment may require significantly more savings.
Moderate-Cost U.S. Areas
In a smaller city, suburb, or rural community, $4,000 can provide a much more comfortable lifestyle—particularly if your mortgage is already paid off.
Eliminating a $1,500 or $2,000 monthly housing payment can completely change the retirement equation.
Lower-Cost International Destinations
Some retirees also consider countries where everyday expenses can be substantially lower than in major U.S. cities.
Places such as Portugal, Mexico, Thailand, and Ecuador can offer opportunities for retirees seeking lower living costs, although taxes, healthcare, visas, housing, and exchange-rate fluctuations must also be considered.
This strategy is often referred to as geoarbitrage: earning or investing in one economic environment while living in another with a lower cost of living.
How Much Do You Need to Retire Early?
One of the most commonly discussed guidelines in retirement planning is the 4% rule.
Under the traditional framework, a retiree withdraws approximately 4% of an investment portfolio during the first year of retirement and then adjusts withdrawals for inflation.
If you need $48,000 per year entirely from your investments:
$48,000 ÷ 0.04 = $1.2 million
That gives you a rough portfolio target of $1.2 million.
However, this should not be treated as a guarantee.
The 4% rule was developed from historical market data and is a planning guideline, not a promise that your money will never run out. Early retirees may need a more conservative withdrawal rate because their retirement could last 40, 50, or even more years.
What If You Have Other Income?
Your required investment portfolio can be considerably smaller if part of your $4,000 monthly income comes from other sources.
For example:
| Monthly Income Source | Amount |
|---|---|
| Investment withdrawals | $2,000 |
| Part-time/consulting income | $1,000 |
| Rental or other income | $1,000 |
| Total | $4,000 |
In this scenario, your portfolio doesn’t need to generate the entire $48,000 annually.
That’s an important distinction because reducing the amount you need to withdraw from investments can make early retirement considerably more sustainable.
A Sample $4,000 Monthly Retirement Budget
Consider a couple living in a relatively affordable area with a fully paid-off home.
A potential monthly budget could look like this:
| Expense | Monthly Budget |
|---|---|
| Property taxes, insurance & maintenance | $500 |
| Groceries | $600 |
| Healthcare & medical expenses | $600 |
| Transportation | $400 |
| Utilities & internet | $250 |
| Dining, entertainment & hobbies | $400 |
| Travel | $400 |
| Miscellaneous & financial buffer | $350 |
| Long-term savings | $500 |
| Total | $4,000 |
This budget is possible, but it isn’t overly generous.
A major home repair, unexpected medical expense, vehicle replacement, or family financial obligation could quickly put pressure on the plan.
That’s why early retirement requires more than simply making the monthly numbers work.
You need financial margin.
5 Things You Need Before Retiring Early
1. Eliminate High-Cost Debt
Entering early retirement with credit-card balances, expensive car loans, or a large mortgage can make a $4,000 monthly budget extremely difficult.
Debt payments create fixed obligations that don’t disappear when investment markets decline.
The closer you can get to being debt-free before retiring, the more flexibility you’ll have.
2. Have a Healthcare Strategy
Healthcare is one of the biggest challenges facing Americans who retire before becoming eligible for Medicare.
If you retire before 65, you may need to rely on an employer-sponsored spouse plan, an ACA Marketplace plan, or another source of coverage.
Healthcare costs can vary significantly depending on age, location, income, plan selection, and subsidies.
A retirement plan that ignores healthcare isn’t complete.
3. Build a Large Emergency Reserve
Traditional workers have future paychecks to help absorb unexpected expenses.
Early retirees don’t.
Consider maintaining a substantial cash or short-term Treasury reserve so you aren’t forced to sell investments during a market downturn.
This can also help manage sequence-of-returns risk—the danger of experiencing poor investment returns early in retirement when you’re simultaneously withdrawing money from your portfolio.
4. Account for Inflation
$4,000 today will not have the same purchasing power 20 or 30 years from now.
At an average inflation rate of 3%, prices would roughly double over a 24-year period.
That means your retirement portfolio needs to continue growing even after you stop working.
For many retirees, maintaining exposure to stocks and other growth-oriented investments is an important part of protecting long-term purchasing power.
5. Create a Backup Income Strategy
One of the smartest ways to make early retirement more resilient is to have an income “escape hatch.”
Consulting, freelancing, seasonal work, online business income, or part-time employment can provide additional cash during difficult market periods.
Even an extra $1,000 per month equals $12,000 per year.
More importantly, earning a little during a market downturn can allow you to reduce investment withdrawals when your portfolio is under pressure.
What Lifestyle Does $4,000 Require?
Retiring early on $4,000 per month doesn’t necessarily mean living an extremely frugal life.
It does, however, require intentional spending.
You may need to:
- Cook at home regularly
- Limit expensive restaurant meals
- Drive reliable used vehicles
- Avoid unnecessary consumer debt
- Travel during less expensive seasons
- Compare insurance and utility costs
- Prioritize experiences over expensive possessions
- Maintain a reasonable housing cost
- Avoid lifestyle inflation
The goal isn’t necessarily to spend as little as possible.
The goal is to spend heavily on what matters to you and cut aggressively on what doesn’t.
For some retirees, that can actually lead to a more satisfying lifestyle.
Can a Single Person Retire on $4,000 a Month?
Absolutely—but location becomes especially important.
A single homeowner with no mortgage, $1.2 million or more invested, manageable healthcare costs, and modest spending could potentially make $4,000 per month work.
A single renter living in an expensive metropolitan area may need substantially more.
This illustrates why retirement planning should never rely on a single universal number.
Two people earning and spending $4,000 per month can have completely different financial realities.
What About a Couple?
A couple may have an advantage because many expenses can be shared.
One home, one internet connection, shared utilities, and potentially shared transportation can reduce the cost per person.
However, couples also need to account for potentially higher healthcare expenses, travel costs, and the possibility that both people may live for several decades in retirement.
The goal should be to create a budget that remains sustainable even when unexpected expenses appear.
The Bottom Line
Yes, you can retire early on $4,000 per month—but the number only works when the rest of your financial plan works with it.
If you need $48,000 annually from investments alone, the traditional 4% framework points to approximately $1.2 million in invested assets. But your actual target may be higher or lower depending on your withdrawal strategy, retirement timeline, taxes, healthcare costs, Social Security expectations, and other income sources.
A debt-free homeowner living in a moderate-cost location with $1.2 million or more invested may have a realistic path to early retirement.
A renter in an extremely expensive city with significant debt and limited savings faces a very different situation.
Ultimately, the most important question isn’t:
“Is $4,000 a month enough to retire?”
It’s:
“Can I build a life I genuinely enjoy for $4,000 a month—and can my financial plan sustain that lifestyle for decades?”
If the answer is yes, early retirement may be much more achievable than you think. Click in Read Next: